BNPL, Rates, Tariffs, Bonds and Unemployment: What Do They Have to Do With Each Other?
Pay in 4 looks like a checkout feature. It is a loan, and loans live and die by the cycle.
A loan with a friendly button
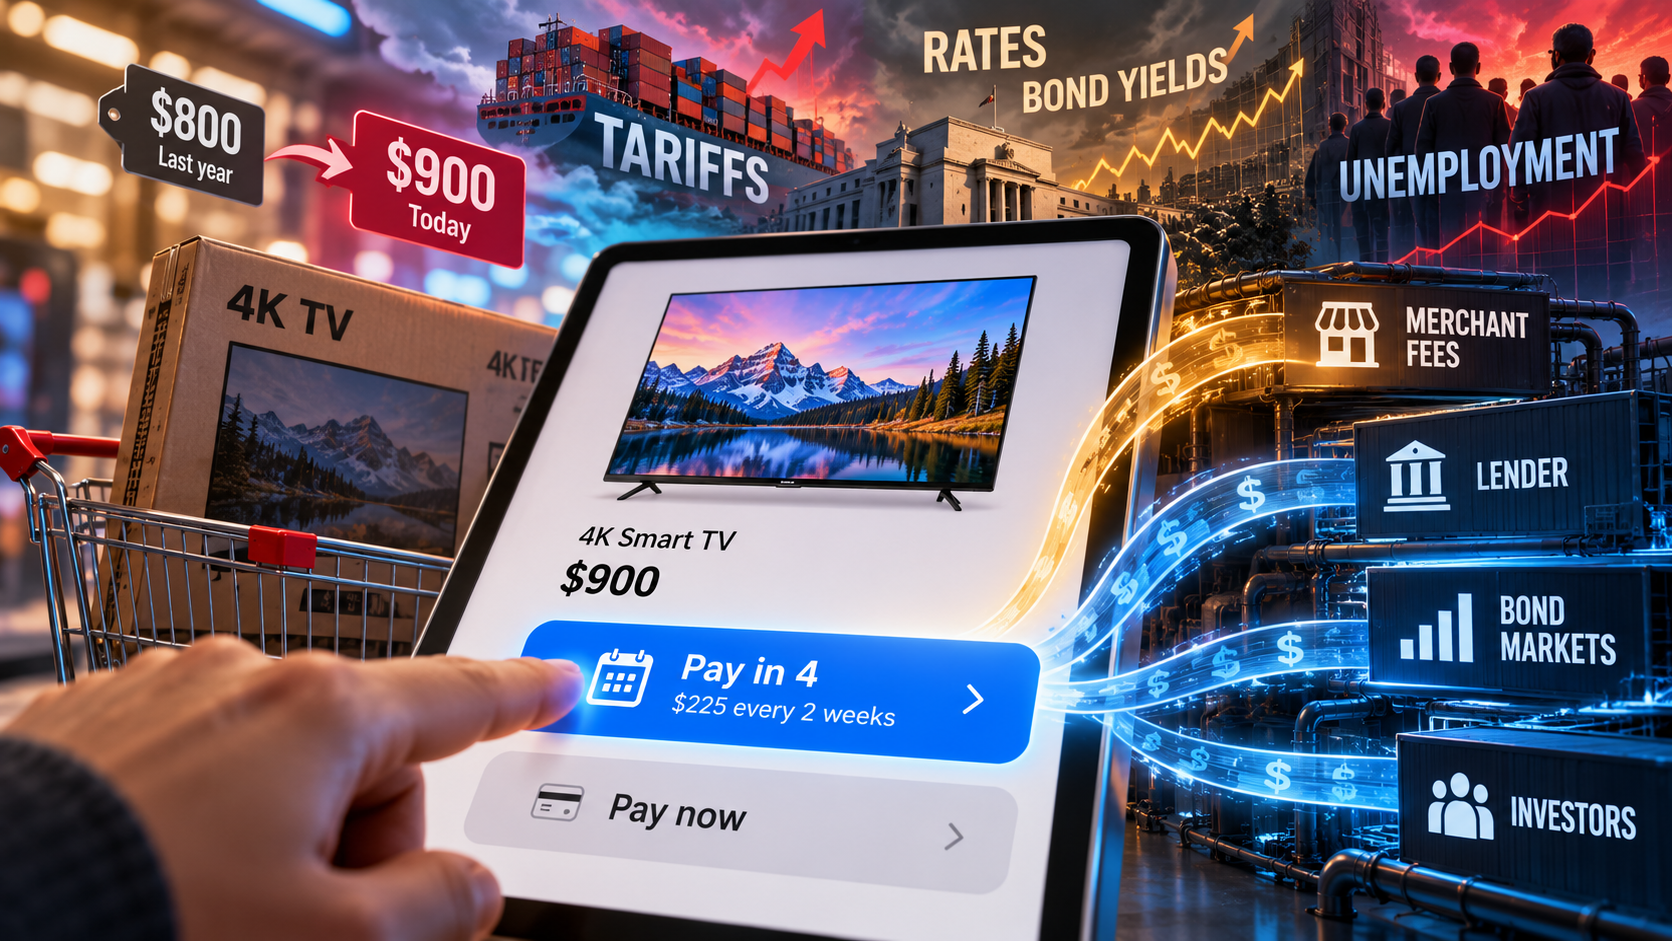
A television that cost $800 last year costs $900 today. Nobody's paycheck went up a hundred dollars to match, so at checkout plenty of people do the sensible thing and split it into four payments.
That button looks like a payments feature, but in fact, it is really a loan. Once you see it as a loan, everything in the wider economy starts to matter: rates, bond yields, tariffs, unemployment.
When you let someone pay later, someone else has to put up the money now to pay the seller. The experience may not make that apparent, and the shopper sees 0%, but somebody is still paying for it. Usually the merchant contributes, through a fee that tends to run well above what a card costs them. The provider — in this case, for clarity, I will name it the lender — covers the rest: what it costs to borrow the money it lends, and the customers who never pay it back.
So far things keep looking pretty simple, so let's unravel the complexity a bit more, just because BNPL is in fact much more than a button or option at checkout.
Tariffs push both ways
Higher prices make installments more appealing, don't they? Isn't $900 harder to swallow in one go than $800 was? I wish it were that easy, but it isn't: the same conditions that push prices up can also make the money behind those installments more expensive.
Now, I will introduce one more element — just for fun. The bond market is where that expense shows up. BNPL companies do not lend out of their own pockets. Most of them borrow from banks, sell their loans to private credit funds, and package them into securities for investors, and when bond markets get nervous about inflation, government debt, or where rates are heading, all of that borrowing gets more expensive.
How much it hurts depends on the ticket size as well as the term. On a six-week Pay in 4 plan and a small purchase, the cost of money barely registers. On a two-year monthly plan for an expensive purchase, it will painfully add up.
Unemployment is the part I watch most
Up to this point the question has been whether people can afford to buy. When unemployment rises, the question becomes whether they can afford to pay back, and that is a much harder problem.
Imagine prices staying high, more people leaning on installments, money staying expensive, and then layoffs starting. BNPL is most useful to shoppers at the exact moment it is most dangerous for lenders. Add the fact that one person can hold plans with three lenders who cannot see each other, and trouble can build quietly before it shows up in the numbers.
To be fair, BNPL has one real advantage in a downturn. Its loans are short, so a lender that tightens approvals sees the effect within weeks, while a credit card portfolio takes far longer to turn. Whether lenders actually move that fast, and how merchants react when fewer of their customers get approved, is a totally different story.
Rails versus lending
This is why I do not like lumping BNPL in with Visa, Mastercard, ACH, wallets or real-time payments. Those are the pipes or rails money moves through. BNPL is a lending decision sitting on top of those pipes, the same way a credit card's credit line sits on top of the card network. And lending always depends on what the economy is doing.
Whether people like BNPL is not for debate here. Clearly many do. The more useful questions are about what happens when the cycle turns. Who is putting up the money, and what is it costing them? Who absorbs the losses? How fast can approval standards change, and what does that do for merchants? And what happens when shoppers need installments the most?
My guess is that BNPL will matter most right when it is hardest to make money on. That is when people will stop seeing it as a checkout button and start seeing it as what it is: a loan, with the whole economy riding on it.
Franco Di Pietro
The Payments Corner
30+ years across payments, fintech, banking, and financial infrastructure. Operator-level perspectives on the systems that move money.
Related Insights
Financial institutions simplified transactions but left consumers struggling to understand the consequences
Payment infrastructure has become nearly invisible to users, but the complexity of financial obligations—credit card statements, dispute procedures, BNPL layering—remains opaque. The industry invested decades in frictionless access; it has invested far less in ensuring people understand what they are actually committing to.
Consumers are treating loyalty rewards as routine financial tools, not aspirational bonuses
Rising cost-of-living pressure is shifting how households use payment rewards—from occasional indulgences toward deliberate, everyday value recovery. If rewards are becoming part of baseline spending optimization rather than spending stimulation, loyalty program design and success metrics may need to reset.
A alta das fintechs brasileiras foi uma aposta em juros
As fintechs brasileiras subiram bem mais que o mercado depois do primeiro turno e seguiram em alta quando o índice parou. A eleição foi o gatilho; quem sustentou o movimento foi a curva de juros.